
Understanding the Three Major Financial Statements for Business Success

A business can look busy and still be in trouble. Sales may be coming in, customers may be happy, and the team may feel stretched, yet cash can still run short or debt can quietly build.
That is why the three major financial statements matter. The balance sheet, income statement, and cash flow statement each tell a different part of the same story. Read together, they show what the business owns, what it owes, how much profit it earns, and whether cash is actually available to pay the bills.
This guide is informational only and should not replace advice from a qualified accountant or financial professional. Still, understanding the basics can help any business owner ask better questions and make smarter decisions.

The three statements work together
Each major financial statement answers a different question.
Financial statement | Main question it answers | What it helps you see |
Balance sheet | What does the business own and owe right now? | Assets, liabilities, and equity |
Income statement | Did the business make a profit over a period of time? | Revenue, expenses, and net income |
Cash flow statement | Where did cash come from and where did it go? | Operating, investing, and financing cash activity |
A common mistake is looking at only one statement. That can lead to false confidence.
For example, a business may show a profit on the income statement but still struggle to pay suppliers because customers have not paid their invoices. Another business may have cash in the bank after taking out a loan, but the balance sheet will show the debt that comes with it.
The statements are strongest when used together. They help answer practical questions such as:
Can the business afford to hire?
Is debt becoming too high?
Are sales covering expenses?
Is inventory tying up too much cash?
Are late customer payments creating pressure?
Is growth helping the business or draining cash?
Think of the three statements as different views of the same business. One view is not enough.
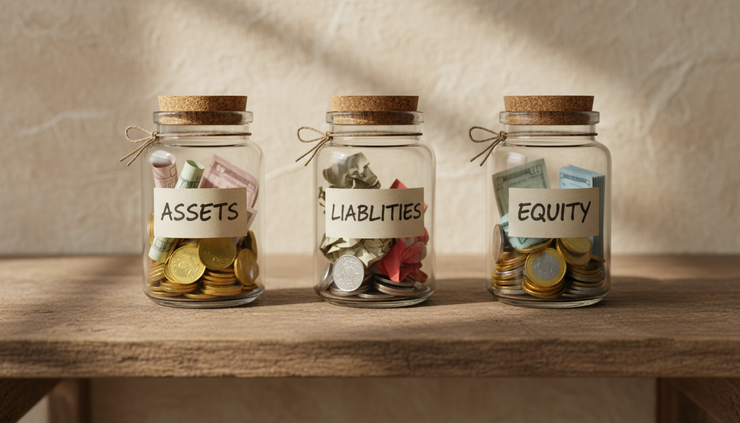
The balance sheet shows what the business is worth at a point in time
The balance sheet is a snapshot. It shows the financial position of a business on a specific date, such as December 31 or the last day of a month.
It follows a basic accounting equation:
Assets = Liabilities + Equity
That equation must stay in balance, which is why the statement has its name.
Assets show what the business owns
Assets are resources the business owns or controls. They can be used to run the business, pay obligations, or support future growth.
Common assets include:
Cash in bank accounts
Accounts receivable from customers
Inventory
Equipment
Vehicles
Buildings or land
Prepaid expenses
Security deposits
Assets are often grouped into current and long-term categories.
Current assets are expected to turn into cash or be used within one year. Cash, accounts receivable, and inventory usually fall here.
Long-term assets help the business over a longer period. Equipment, vehicles, and property are common examples.
The asset section helps answer a simple question: what resources does the business have available?
Liabilities show what the business owes
Liabilities are debts and obligations. They show money the business must pay in the future.
Examples include:
Credit card balances
Supplier bills
Payroll taxes payable
Sales tax payable
Bank loans
Equipment loans
Lease obligations
Customer deposits
Like assets, liabilities are usually split into current and long-term categories.
Current liabilities are due within one year. Supplier bills, short-term loans, and taxes payable are common examples.
Long-term liabilities are due after more than one year. A five-year equipment loan would usually fit here.
Liabilities matter because they show pressure on future cash. A business with strong sales can still face trouble if too many obligations come due at once.
Equity shows the owner’s financial stake
Equity is what remains after subtracting liabilities from assets. For a small business, this often includes owner contributions and retained earnings.
Retained earnings are profits kept in the business rather than distributed to owners.
If assets are much higher than liabilities, equity is positive. If liabilities are higher than assets, equity can become negative, which may signal financial weakness.
The balance sheet is especially useful for spotting trends. Over time, look for changes in:
Cash balances
Accounts receivable
Inventory
Debt
Owner’s equity
A single balance sheet gives a snapshot. Several balance sheets together show direction.
The income statement shows whether the business is profitable
The income statement, sometimes called the profit and loss statement or P&L, shows financial performance over a period of time. That period may be a month, quarter, or year.
It answers one main question: did the business earn more than it spent?
The basic structure is:
Revenue - Expenses = Net Income
If revenue is higher than expenses, the business has net income. If expenses are higher than revenue, it has a net loss.
Revenue shows what the business earned
Revenue is income from selling goods or services. A bakery earns revenue from selling bread, cakes, and coffee. A landscaping company earns revenue from mowing lawns, installing plants, and maintaining properties.
Some businesses have several revenue streams. Separating them can be useful.
For example, a repair shop may track:
Service labor
Replacement parts
Maintenance plans
Emergency calls
This helps show which parts of the business are growing and which may need attention.
Revenue should not be confused with cash collected. If a customer buys on credit, the income statement may show revenue before cash arrives. That is one reason the cash flow statement matters.
Cost of goods sold shows direct costs
Cost of goods sold, often called COGS, includes costs directly tied to producing or delivering what the business sells.
For a product-based business, this may include:
Raw materials
Packaging
Freight-in
Direct production labor
For a service business, direct costs may include subcontractor labor, supplies used on jobs, or job-specific materials.
Subtracting COGS from revenue gives gross profit.
Gross profit shows how much money remains after direct costs. If gross profit is shrinking, prices may be too low, supplier costs may be rising, or waste may be too high.
Operating expenses show the cost of running the business
Operating expenses keep the business running but are not always tied to one specific sale.
Common operating expenses include:
Rent
Utilities
Insurance
Software subscriptions
Wages and salaries
Payroll taxes
Repairs and maintenance
Professional fees
Telephone and internet
Vehicle expenses
After subtracting operating expenses, the business arrives at operating income.
Some income statements also include interest, taxes, depreciation, and other non-operating items before reaching net income.
Net income is not the same as cash
Net income is an important number, but it does not tell the full story.
A business may show net income while cash is tight because:
Customers have not paid invoices yet
Inventory purchases used cash
Loan payments reduced bank balances
Equipment purchases used available funds
Owner draws reduced cash
The income statement is best for understanding profitability. It helps show whether prices, sales volume, and expenses are working together in a healthy way.
A useful habit is to compare the income statement across months. Look for patterns:
Are sales rising but profit staying flat?
Are labor costs growing faster than revenue?
Are certain expenses increasing without a clear reason?
Does profit drop during slow seasons?
Are discounts cutting too far into margins?
Profit gives the business staying power. Without it, growth can become expensive.
The cash flow statement shows how money moves
The cash flow statement tracks cash coming in and going out during a period. It helps answer a question that every business must face: did cash increase or decrease, and why?
Cash flow is different from profit. Profit follows accounting rules. Cash flow follows the bank account.
A business can survive a short period without profit if it has enough cash and a clear plan. It cannot survive long without cash to pay wages, suppliers, rent, taxes, and loan payments.
The cash flow statement is usually divided into three sections.
Operating activities show cash from daily business
Operating cash flow comes from the core business.
Cash inflows may include:
Customer payments
Cash sales
Collections on invoices
Cash outflows may include:
Supplier payments
Payroll
Rent
Utilities
Insurance
Taxes
Other regular operating costs
This is often the most important section. A healthy business should aim to generate positive cash flow from operations over time.
If operating cash flow is negative month after month, the business may be relying on loans, owner contributions, or delayed payments to stay open.
Investing activities show cash used for long-term assets
Investing activities involve buying or selling long-term assets.
Examples include:
Buying equipment
Selling a vehicle
Purchasing property
Upgrading major machinery
A negative number in this section is not always bad. It may mean the business is investing in tools or equipment that support future growth.
The key is whether those purchases make sense given the company’s cash position and expected return.
Financing activities show cash from owners and lenders
Financing activities show how the business raises or returns money.
Cash inflows may include:
Bank loans received
Owner contributions
Investor funding
Cash outflows may include:
Loan principal payments
Owner draws or distributions
Dividends
This section helps separate borrowed cash from earned cash. That distinction matters.
A business may show a cash increase because it borrowed money. That can be useful, but it is not the same as cash generated by operations.
Cash flow reveals timing problems
Timing is one of the most common causes of stress in small businesses.
Imagine a contractor finishes a large job in April and sends an invoice for $40,000. The income statement may show the revenue in April. But if the customer pays in June, the business still needs cash in April and May for payroll, materials, insurance, fuel, and other costs.
The cash flow statement helps reveal this gap.
Common causes of cash flow pressure include:
Slow-paying customers
Too much inventory
Large upfront job costs
Seasonal sales swings
High loan payments
Owner draws that exceed available cash
Tax payments that were not planned for
Strong cash management does not mean avoiding every expense. It means knowing when cash will come in, when it must go out, and whether the business has enough cushion.
How to use the statements to make better decisions
Financial statements should not sit untouched until tax season. They are decision tools.
A good monthly review can help catch small problems early. Start with a few questions for each statement.
Questions to ask about the balance sheet
Look for strength, risk, and changes in financial position.
Ask:
Is cash increasing or decreasing?
Are customer invoices being collected on time?
Is inventory growing faster than sales?
Are liabilities rising too quickly?
Is equity improving over time?
If accounts receivable keeps growing, sales may look strong while cash weakens. If debt is rising but revenue is flat, the business may be borrowing to cover operating problems.
Questions to ask about the income statement
Look for profit quality.
Ask:
Are sales high enough to cover direct costs?
Is gross profit stable?
Which expenses are rising fastest?
Are price increases needed?
Are some products or services more profitable than others?
A business can improve profit in several ways. It can raise prices, reduce waste, renegotiate supplier costs, improve scheduling, or stop selling low-margin products that drain resources.
Questions to ask about the cash flow statement
Look for cash timing and survival risk.
Ask:
Is cash from operations positive?
Are late payments creating a cash gap?
Are loan payments manageable?
Are large purchases planned around cash availability?
Does the business have enough cash for taxes and slow periods?
Cash flow planning can prevent rushed decisions. It gives time to collect receivables, adjust spending, arrange financing, or delay a purchase before pressure builds.

Common mistakes to avoid when reading financial statements
Many business owners read financial statements only at a surface level. The numbers become more useful when common mistakes are avoided.
Looking only at sales
Sales growth feels good, but sales alone do not prove success. If costs rise faster than revenue, profit can fall. If customers pay late, cash can shrink even when sales rise.
Track sales, but pair them with gross profit, net income, and operating cash flow.
Treating profit as spendable cash
Net income does not always equal cash in the bank. Some profit may be tied up in unpaid invoices, inventory, or assets. Some cash may be needed for loan payments or taxes.
Before making a major purchase or owner distribution, check both profit and cash.
Ignoring the balance sheet
The income statement often gets the most attention because it shows profit. But the balance sheet may reveal growing debt, weak cash reserves, stale inventory, or unpaid obligations.
A profitable business with a weak balance sheet can still be exposed to risk.
Reviewing statements too late
Financial statements are most useful when they are current. If books are months behind, the business is making decisions with old information.
Monthly reviews are a practical rhythm for many businesses. Some businesses with tight margins or seasonal swings may need weekly cash flow checks.
Failing to compare periods
One statement on its own has limited value. Comparing this month to last month, this quarter to last quarter, or this year to last year reveals trends.
Trends often matter more than one number. A single slow month may be normal. A steady decline in gross profit needs attention.
The real value is better judgment
The balance sheet, income statement, and cash flow statement are not just accounting reports. They are a practical way to understand how a business is really doing.
The balance sheet shows financial position. The income statement shows profitability. The cash flow statement shows whether cash is moving in a healthy way.
Used together, they help turn scattered financial details into clearer judgment. That judgment can guide pricing, hiring, borrowing, spending, saving, and growth.
Start with a simple routine. Review the three statements each month, ask direct questions, and follow the trends. A business does not need perfect numbers to improve. It needs clear numbers, reviewed often, and used before decisions are made.


Comments